Finance Exams
Best FRM Part 1 Anki — 444 Cards + Free Timed Mock
444 cards across FRM Part 1 foundations, quant, markets, and valuation. The free start is 25 questions. The full timed readiness check is 50 questions.
One-time purchase · .apkg for Anki (desktop, AnkiMobile, AnkiDroid) · instant download via Gumroad
Not ready to buy? Take the free 25-question diagnostic →
81 people have purchased this deck. Recent UniPrep2Go checkout activity — not an official exam board figure.
Exam version & sources
Financial Risk Manager (FRM) Part 1— what this product is (and isn't)
- Exam version
- 2026 FRM Learning Objectives (GARP)
- Official source
- GARP — FRM exam information
- Last reviewed
- October 16, 2026
- What this covers
- 444 cards — All four FRM Part 1 books, weighted 20/20/30/30 like the exam, across 62 reading-level sections
- Does not replace
- Independent study aid — it does not replace GARP Learning curriculum, practice questions, and practice exams.
Free practice test
FRM Part 1 Practice Questions — 25Q Free, 50Q Mock 2026
FRM Part 1 knowledge diagnostic — 50-question timed check (free 25-question version) with topic scoring and a readiness report before you buy the deck. It checks what you know; it is not a copy of the official exam format.
Take the free 25-question diagnosticSample cards
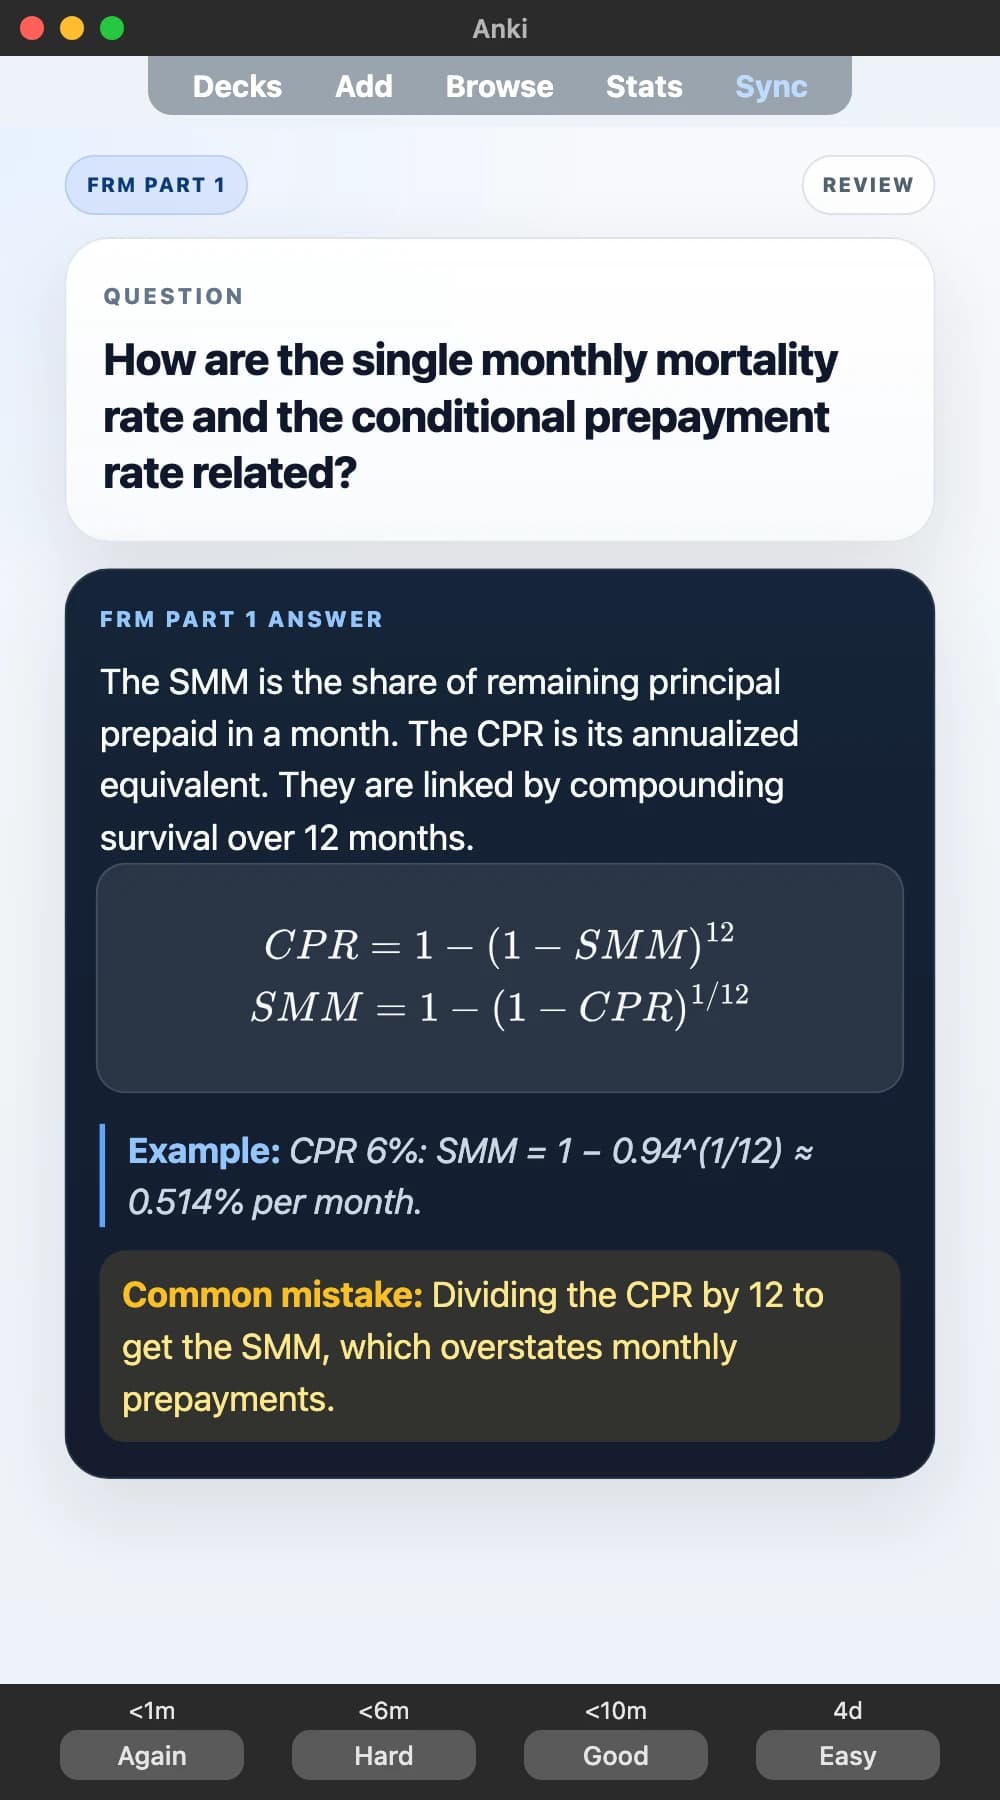
How are the single monthly mortality rate and the conditional prepayment rate related?
The SMM is the share of remaining principal prepaid in a month. The CPR is its annualized equivalent. They are linked by compounding survival over 12 months.
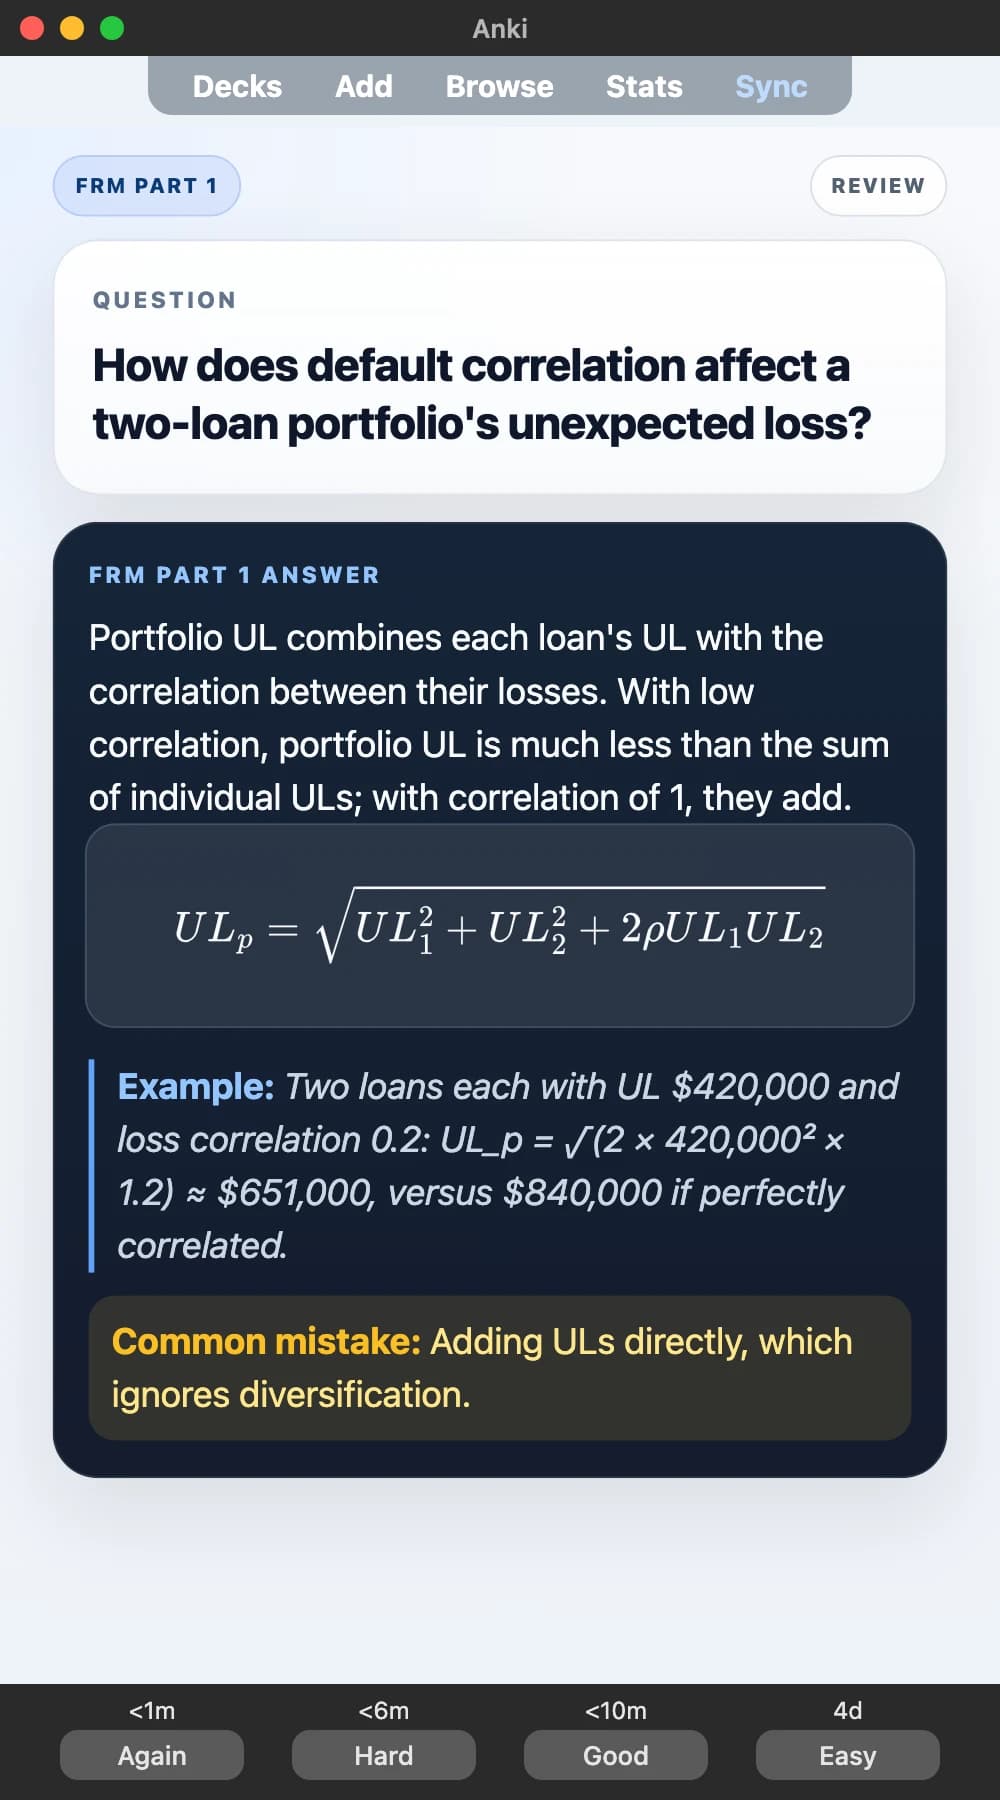
How does default correlation affect a two-loan portfolio's unexpected loss?
Portfolio UL combines each loan's UL with the correlation between their losses. With low correlation, portfolio UL is much less than the sum of individual ULs; with correlation of 1, they add.
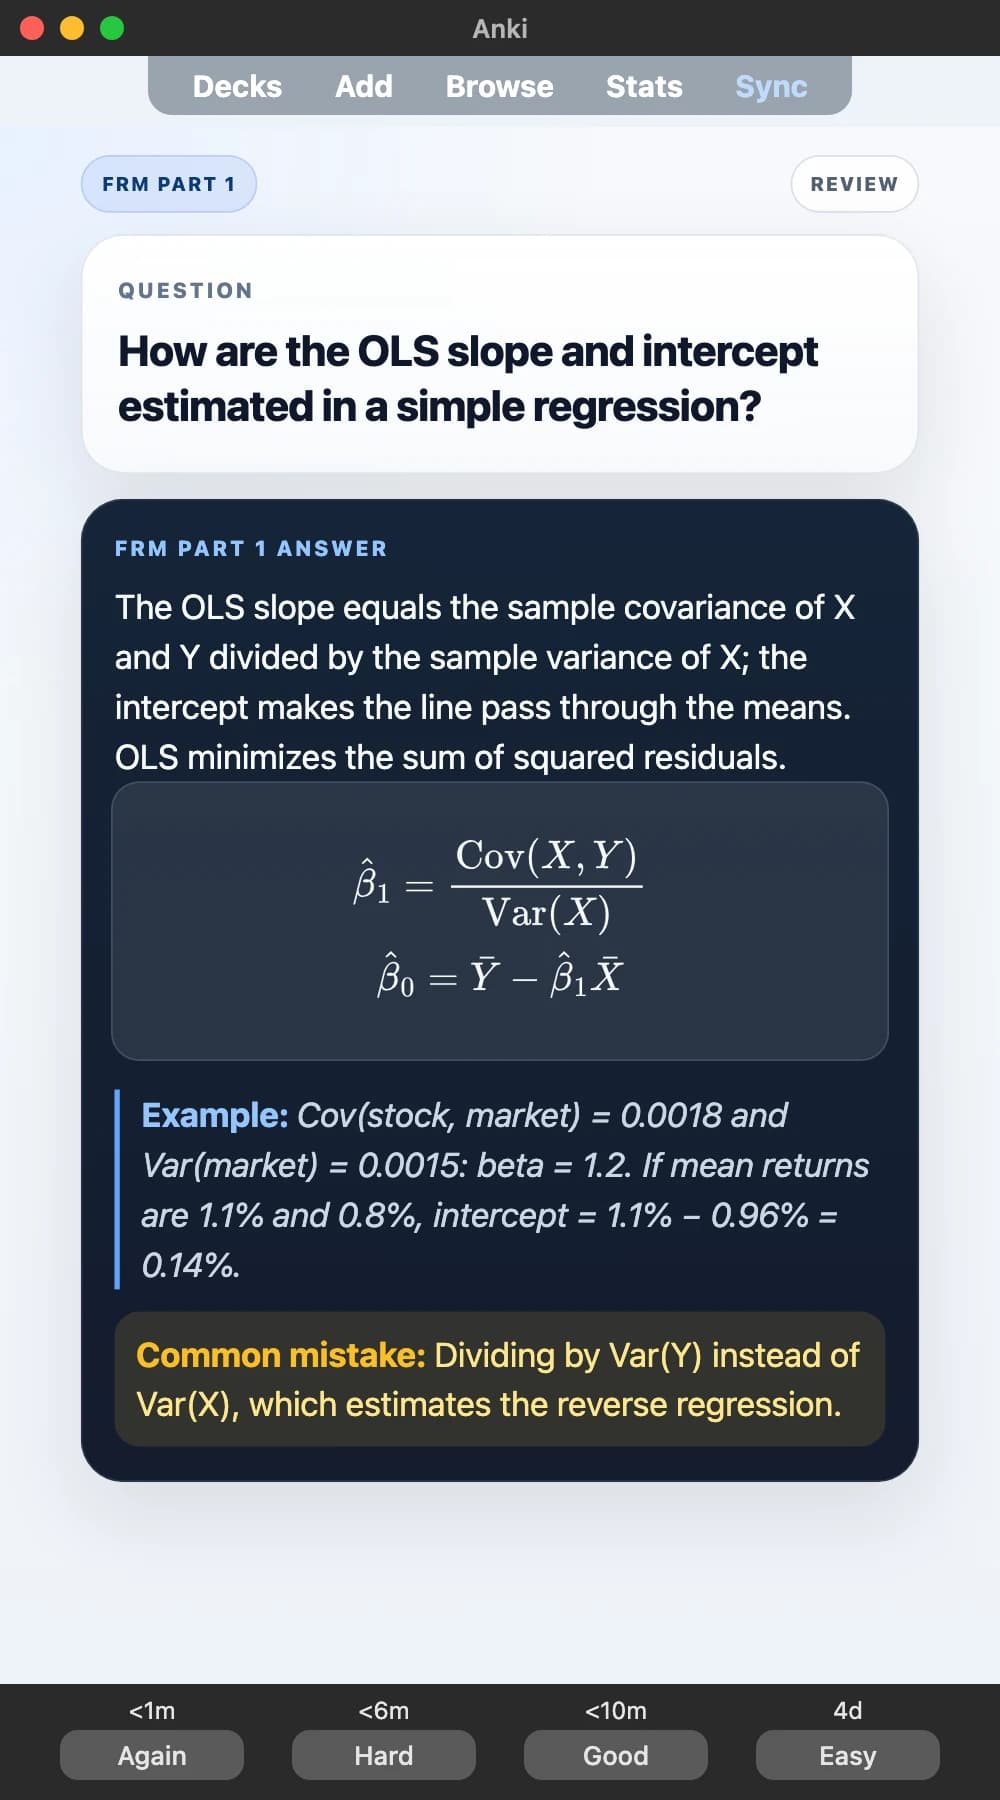
How are the OLS slope and intercept estimated in a simple regression?
The OLS slope equals the sample covariance of X and Y divided by the sample variance of X; the intercept makes the line pass through the means. OLS minimizes the sum of squared residuals.
Ready to drill with the full deck?
Instant .apkg download after Gumroad checkout.
Get 444-Card FRM Part 1 Deck — $29 USDProduct facts
- Cards
- 444
- Coverage
- All four FRM Part 1 books, weighted 20/20/30/30 like the exam, across 62 reading-level sections
- Format
- .apkg
- Price
- $29 USD
- Checkout
- Gumroad
- Exam cycle
- 2026 FRM Part 1 Learning Objectives (GARP)
- Delivery
- Digital download through Gumroad (460 KB)
Coverage by exam topic
| Topic | Exam weight | Cards |
|---|---|---|
| Foundations of Risk Management | 20% of Part I | 89 |
| Quantitative Analysis | 20% of Part I | 89 |
| Financial Markets and Products | 30% of Part I | 133 |
| Valuation and Risk Models | 30% of Part I | 133 |
Exam facts
Financial Risk Manager (FRM) Part 1
FRM Part 1 is the first of two exams for the Financial Risk Manager certification administered by GARP. This page summarizes structure, topic weights, and independent UniPrep2Go study products (not official GARP material).
- Questions
- 100 equally weighted multiple-choice questions
- Time
- 4 hours
- Passing score
- No fixed passing score published; GARP sets the cutoff each cycle
- Delivery
- Computer-based at Pearson VUE test centers
- Administered by
- Global Association of Risk Professionals (GARP)
Knowledge domains and weights
| Domain | Official weight |
|---|---|
| Foundations of Risk Management | 20% |
| Quantitative Analysis | 20% |
| Financial Markets and Products | 30% |
| Valuation and Risk Models | 30% |
High-yield facts (commonly tested)
- Value at Risk (VaR) estimates the maximum loss over a horizon at a given confidence level.
- Delta measures the sensitivity of an option's price to the underlying asset price.
- Credit risk is the risk of loss from a counterparty's failure to meet contractual obligations.
- Basel frameworks set capital requirements for banking institutions.
- Expected shortfall (CVaR) averages losses beyond the VaR threshold.
- Passing Part I alone is not certification — you must pass Part II and submit two years of relevant work experience.
Common Financial Risk Manager (FRM) Part 1 questions
Straight answers to the questions candidates usually search before buying prep or booking the exam.
How many questions are on FRM Part 1?
100 equally weighted multiple-choice questions in 4 hours.
What are the FRM Part 1 topic weights?
Foundations of Risk Management (20%), Quantitative Analysis (20%), Financial Markets and Products (30%), Valuation and Risk Models (30%).
Do you need to pass FRM Part 1 before Part 2?
Yes. Candidates must pass Part 1 before Part 2 can be graded.
Verify current exam fees, scheduling, and administrative details at www.garp.org/frm/program-exams. Independent study aid — not official exam material.
More about FRM Part 1Study tips, positioning, and how this deck compares
FRM Part 1 exam prep
Cards track GARP Part 1 structure: risk governance, VaR and Expected Shortfall, credit and operational risk, fixed income and derivatives Greeks. The free FRM mock scores topic gaps so you drill valuation models and market mechanics — not random card volume.
Built for: FRM Part 1 candidates who want active recall practice for formulas, concepts, definitions, and risk-management logic.
Covers: All four FRM Part 1 books, weighted 20/20/30/30 like the exam, across 62 reading-level sections.
- Spaced-repetition flashcards
- 444 exam-focused flashcards
- Topic coverage table and samples on this page
- Linked 50-question practice test (free 25-question version)
How this deck compares
Q-bank subscriptions win on question volume. UniPrep wins when you want an ownable Anki file plus one free timed diagnostic — $29 once, then daily spaced repetition on VaR/ES/Greeks gaps the mock surfaces.
| Approach | Typical size | Tradeoffs |
|---|---|---|
| Free community decks | 1,000–3,000 |
|
| Budget mega-packs | 1,000+ |
|
| This deck | 444 exam-focused flashcards |
|
FRM Part 1 study guide
What is inside
444 cards weighted like the exam: 89 Foundations (governance, CAPM and factor models, ERM, case studies such as LTCM and the 2007-09 crisis), 89 Quantitative Analysis (probability, hypothesis tests, regression, time series, volatility, simulation, machine learning), 133 Financial Markets and Products (banks and funds, futures and hedging, options and strategies, swaps, MBS) and 133 Valuation and Risk Models (VaR and ES, GARCH, credit and country risk, operational risk, stress tests, bond pricing, duration and convexity, trees, Black-Scholes-Merton and Greeks). Every card asks a real exam question, explains the rule, works a numeric example where it applies, and names the mistake candidates make.
Plan with the free FRM mock
**Phase 1 (6 weeks out):** 25 cards/day from quant and markets. **Phase 2:** sit the free 25-question start, then the full 50-question mock — remap daily reviews to valuation models and credit if those topics score low. **Final month:** No new cards; ES and VaR calculation prompts daily.
Pitfalls this deck targets
Candidates swap parametric vs historical VaR, mis-state delta-gamma approximations, and confuse settlement conventions on derivatives. Cards flag those calculation boundaries.
Financial Risk Manager (FRM) Part 1 & product FAQ
How many questions are on FRM Part 1?
100 equally weighted multiple-choice questions in 4 hours.
What are the FRM Part 1 topic weights?
Foundations of Risk Management (20%), Quantitative Analysis (20%), Financial Markets and Products (30%), Valuation and Risk Models (30%).
Do you need to pass FRM Part 1 before Part 2?
Yes. Candidates must pass Part 1 before Part 2 can be graded.
What is the best FRM Part 1 Anki deck?
Look for a Part 1–scoped deck with VaR/ES, Greeks, credit risk, and markets cards plus a timed practice test for topic gaps. UniPrep2Go’s FRM Part 1 Anki deck is 444 cards. The free start is 25 questions. The full readiness check is 50 questions.
Is there a free FRM Part 1 practice test?
The free start is 25 questions, no signup. The full FRM Part 1 readiness check is 50 questions at uniprep2go.study/mock-exams/frm-part-1-readiness-check. Each full attempt draws from a 100-question bank in the exam's topic weights, then you drill weak topics in this Anki deck. Your first UniPrep2Go mock, including this FRM Part 1 one, is a free 25-question timed diagnostic (any exam, Exam or Learn mode, no signup); full-length mocks and retakes run on the $5 UniPrep2Go Mock Pass — 5 attempts on any mock.
What file format is delivered?
An Anki-compatible .apkg file delivered through Gumroad.
More questions (1)
Is this affiliated with GARP?
No. This is an independent study aid and is not affiliated with, endorsed by, or sponsored by GARP. FRM is a trademark of the Global Association of Risk Professionals.
Also useful
More Finance Exams prep
CFA Level 1 Anki Deck — 348 Smart Flashcards
Focused 348-card CFA Level 1 Anki deck weighted to the 2026 topic ranges — scenario and calculation cards with a worked example and common mistake on each, plus a 60-question timed mock (free 25-question version).
CFA Level 1 Formula Reference 2026 — 221 Formulas + 22 Standards + 80-Question Drill (PDF)
48-page printable formula reference for the 2026 cycle — 221 typeset formulas with when to use each and the exam trap, 146 definitions, all 22 Standards, and an 80-question recall drill.
SIE Exam Anki Deck — 300 High-Yield Flashcards
A focused Anki deck for FINRA SIE exam active recall.
Series 7 Flashcards — 300 High-Yield Top-Off Cards + Free Timed Mock
Series 7 flashcards: 300 FINRA Top-Off Anki cards + 60-question timed practice test (free 25-question version) — suitability, products, order flow.